
Hurricane Isaias damage? Our adjusters are on the ground in the Panhandle. Call (800) 822-0101 for a free claim review. Isaias claim help →

Insurance Claim Denied? Get a Free Denial Letter Review
Claim denied? Call us before you accept it. We’ll review the denial letter for free.

Our licensed public adjusters handle claims for homes and businesses.

Stuart Hymson
Public Adjuster

Michael Zebold
Public Adjuster

Micaela Villa
Public Adjuster

Alex Barquero
Public Adjuster

Arthur Camayd
Public Adjuster

Tony Azcue
Public Adjuster

Frank Nunez
Public Adjuster
Got a denial letter? Let us read it.
A denial letter is the insurance company’s side of the story, not the final word. Call us with the letter in hand, and a licensed public adjuster will review it against your policy for free. We’ll tell you straight what it takes to turn it around.
Common reasons insurers give for a denial
Policy exclusions and endorsements
Late notice or a missed policy deadline
Wear and tear, age or old damage
Repeated seepage or leakage over time
Faulty workmanship or poor installation
No sign of sudden, accidental damage
An estimate that comes in under your deductible
A late or missing proof of loss
What we check on a denial
Every denial starts with the letter. Roof and water are the two we see most.
Check what they actually cite
A denial should come in writing and name the part of your policy it relies on. Often the reason is an opinion about age, wear, cause or when the damage happened, and opinions can be wrong.
The exact reason they gave
The policy section they quote
What their adjuster or engineer relied on
They blamed age, wear or bad installation
Roof denials often say the damage is wear and tear, old, cosmetic or a defect, or that their engineer found no storm damage. A second inspection with the right documentation can change the answer.
We document the damage ourselves
We show what their inspection missed
We read the denial against your policy
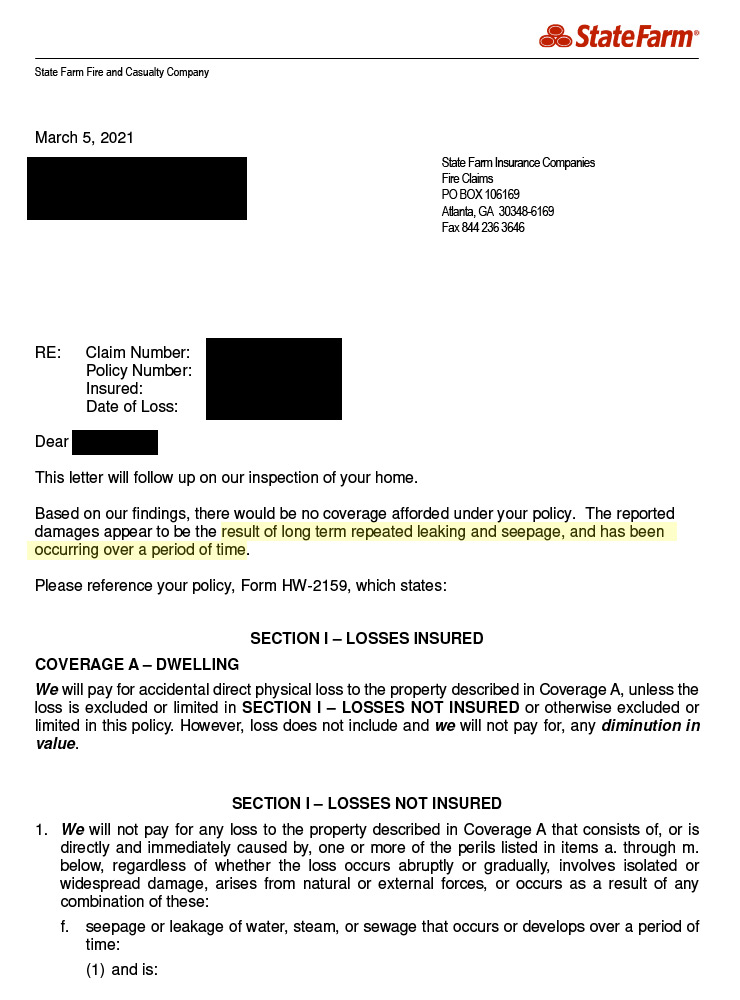
They called it a long-term leak
Water denials often say the leak was continuous or repeated over time, wear and tear, or the pipe itself. Many policies still cover the water damage a sudden leak caused and the cost to tear out what’s needed to reach it.
We trace where the water came from
We document the damage before it’s torn out
We check the exclusion they used against your policy
When the insurance company isn't playing fair
Nearly every state has rules for how insurance companies must handle claims. These are some of the practices those rules call unfair:
Misstating what your policy covers
Not investigating your claim fairly
Not explaining why your claim was denied
Offering far less than your claim is worth
Not answering or acting on your claim promptly
Whether an insurer acted in bad faith is a legal question. We’re public adjusters, not lawyers. What we build is the claim file: the photos, the estimate, the policy and every letter and date. That record shows how your claim was handled. Call us before you accept a denial.
General information, not legal advice.

Fighting for the policyholder
Blueprint Claims has settled over half a billion dollars in commercial and residential claims with 15 years in business. Don’t settle for less, get the money you deserve. Fight for your claim!

Private Equity Firm
Apartment complex

North Port Homeowner
Insurance paid $0

Stone Mountain Homeowner
Insurance paid $0

Property Management
Condominium community
The contractor's edge
Arthur Camayd, partner, is a licensed public adjuster with the SPPA designation, a licensed general contractor, and holds a degree in architecture.
We know how buildings are designed, how they are built, and how to spot the damage most people miss. On complex claims like fires with structural damage or hidden issues, that construction insight and policy knowledge lets us build a stronger claim and challenge a low offer with real authority.
Licensed general contractor
Degree in architecture
SPPA public adjuster
We don’t just estimate. We advocate.
How we handle your claim
Four steps, from the first call to the settlement check.

Free claim consultation
Tell us about your claim. We’re here to help.

Free property inspection
Leaving no stone unturned, we focus on the details.

We estimate & appraise
Don’t worry about having to gather various repair bids on your own.

We negotiate & settle
We don’t get paid unless you get paid.
What to do after a denial
Waiting to see what the insurance company does is how good claims run out of time.
A denial isn't the last word
Insurance companies often deny claims as wear and tear, old damage or not covered. That letter is their side of the story, not the final word. The right proof can change it, but the window to act is short. Call us before you take no for an answer.
Once it's repaired, it's hard to prove
Stop the damage from spreading, but take photos and video before anything is torn out or repaired, and keep what gets replaced. Once the damage is gone, it’s your word against the insurance company’s. Call us first, and we’ll document it the right way.
The clock is already running
We hear it all the time. The insurance company says no, so you call the adjuster one more time and wait. Then months go by, and the deadlines in your policy keep running. Call now, while you still have options.
Don’t wait to see what they do. Call today and let a licensed public adjuster review your options while you still have them. Your policy review is free.
Types of claims we handle
General information, not legal advice.

Why hire your own public adjuster?
Every claim already has an adjuster. The insurance company’s adjuster works for the insurance company. A public adjuster works for you.
A guide through the entire claim process.
Help you understand your rights under the policy.
Navigating through policy endorsements and exclusions.
Document your damages in detail.
Estimating & valuing the TRUE cost of your loss.
Collaboration with experts to support your claim.
Negotiating & settling your claim.
Working with contractors to get you back to pre-loss condition.
Hiring your own adjuster pays for itself.
Meet the adjusters
“Our adjusters know how buildings are built, how policies are written, and how to get a claim to the finish line.”
Michael Zebold, SPPA
Firm Partner

Michael Zebold
Senior Public Adjuster

Arthur Camayd
Senior Public Adjuster

Tony Azcue
Public Adjuster

Frank Nunez
Senior Public Adjuster
See what our clients are saying
“Frank Nunez was extremely helpful in getting my claim overturned from a complete denial to a fully paid for roof.”

Ben Justice
“Blueprint Claims did an excellent job. They are the ultimate professionals. After my initial meeting with Alex, he took care of everything.”
D K
“Impeccable work and very effective, from first inspection review to the last step”

Margarita Gomez
“Frank worked for us, not the insurance company, and kept us informed along the way, which was also very helpful.”
Tom Maides
Questions about denied claims
Answers to the questions callers with a denied claim ask us most.
My claim was denied. Can a public adjuster still help?
Often, yes. A denial is the insurer's side of the story, not the final word. We read the letter against your policy, inspect the damage and build the proof to turn it around. Call us before you accept a denial.
What should I do after I get a denial letter?
Keep the letter, your policy and every photo, estimate and email about the claim, and don't throw out damaged materials. Then call us. A licensed public adjuster will read the letter against your policy for free and tell you what it takes to turn it around.
Can I appeal or reopen a denied claim?
Often, yes. New proof, like a proper inspection, photos, a line-by-line estimate or an expert's report, can reopen a claim or change the answer. Your policy and your state's law set deadlines for that, and they keep running after a denial. Call us now, while you still have time.
My roof claim was denied for wear and tear or age. Can you still help?
Often, yes. Insurers blame age, wear or poor installation, or send an engineer who finds no storm damage. We document the damage ourselves, read the denial against your policy, and tell you straight whether it can be turned around. Call us before you accept it.
My water damage claim was denied. What can I do?
Water denials often say the leak was long-term, wear and tear, or the pipe itself. Many policies still cover the water damage a sudden leak caused and the cost of tearing out what's needed to reach it, and the wording decides it. We trace where the water came from, document the damage and read the exclusion they used. Call us before the wall is closed up.
Is my insurance company acting in bad faith?
That's a legal question, and we don't give legal advice. Nearly every state has rules for how insurers must handle claims, and misstating what your policy covers, not investigating fairly, not explaining a denial or offering far less than a claim is worth can break them. What we build is the claim file: the photos, the estimate, the policy and every letter and date. That record shows how your claim was handled. Call us to review your claim.
Do I need a lawyer for a denied claim?
We're licensed public adjusters, not lawyers, and we don't give legal advice. You can always talk to your own lawyer. The right proof can change a denial, and if your claim ever needs a lawyer, we work together with experienced property damage attorneys, and they rely on the file we build: the inspection, the photos and our line-by-line estimate. Call us before you accept a denial, so that file is built right.
How much does it cost to have you review my denial?
The review is free. If you hire us, you pay nothing upfront, and if we don't recover money, you owe us nothing. Our fee is a percentage of what we recover for you, set in writing before you sign, and never more than your state's law allows.
Call and a licensed adjuster will go over your claim with you. The review is free.
Connect with one of our licensed adjusters for a free claim consultation
What happens after you send this
A licensed adjuster contacts you We talk through your claim and answer your questions. The consultation is free.
We review your policy and inspect the damage Also free, with no obligation to hire us.
You decide whether to hire us If you do, we build the claim and negotiate with the insurer.
Let's discuss your claim!
We don’t get paid unless you get paid.
